
Florida mobile and manufactured home insurance
A mobile or manufactured home needs the correct policy form. The build year, model, tie-downs, roof, location, and attached additions may affect carrier options.
Quick answers
Sourced from HUD manufactured housing standards (24 CFR Part 3280) and Florida DFS homeowners guidance. Last verified: August 2026.
Is My Home a Mobile Home, a Manufactured Home, or a Modular Home?
“Mobile home” generally refers to homes built before June 1976, before federal HUD construction standards took effect; “manufactured home” refers to homes built to those HUD standards afterward.
A modular home, by contrast, is built to the same local building code as a site-built home, just constructed off-site. Carriers often treat modular homes more like conventional homes for underwriting purposes.
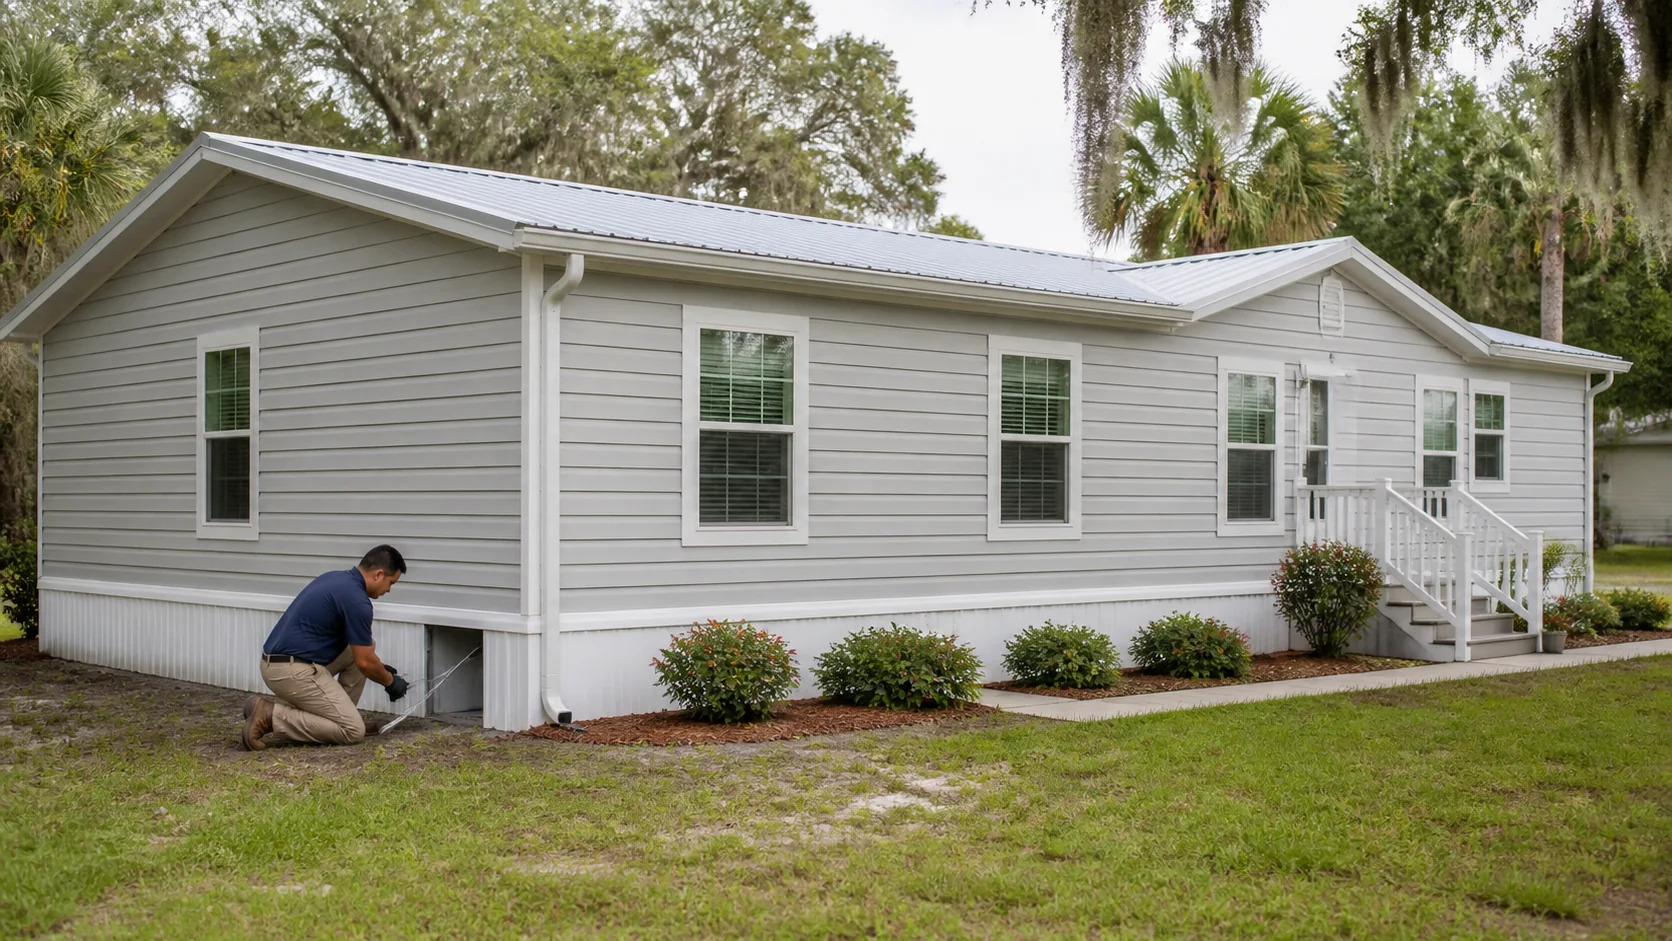
Why Do the Year of Manufacture and the HUD Label Matter to Carriers?
The HUD label (a metal tag affixed to the home) confirms the home was built to federal manufactured-housing standards and shows the date of manufacture, which carriers use to assess age-related risk.
A missing or illegible HUD label can complicate underwriting, since it’s often the clearest way to confirm when and to what standard the home was built.
What Do Carriers Ask About Tie-Downs, Anchoring and the Roof Covering?
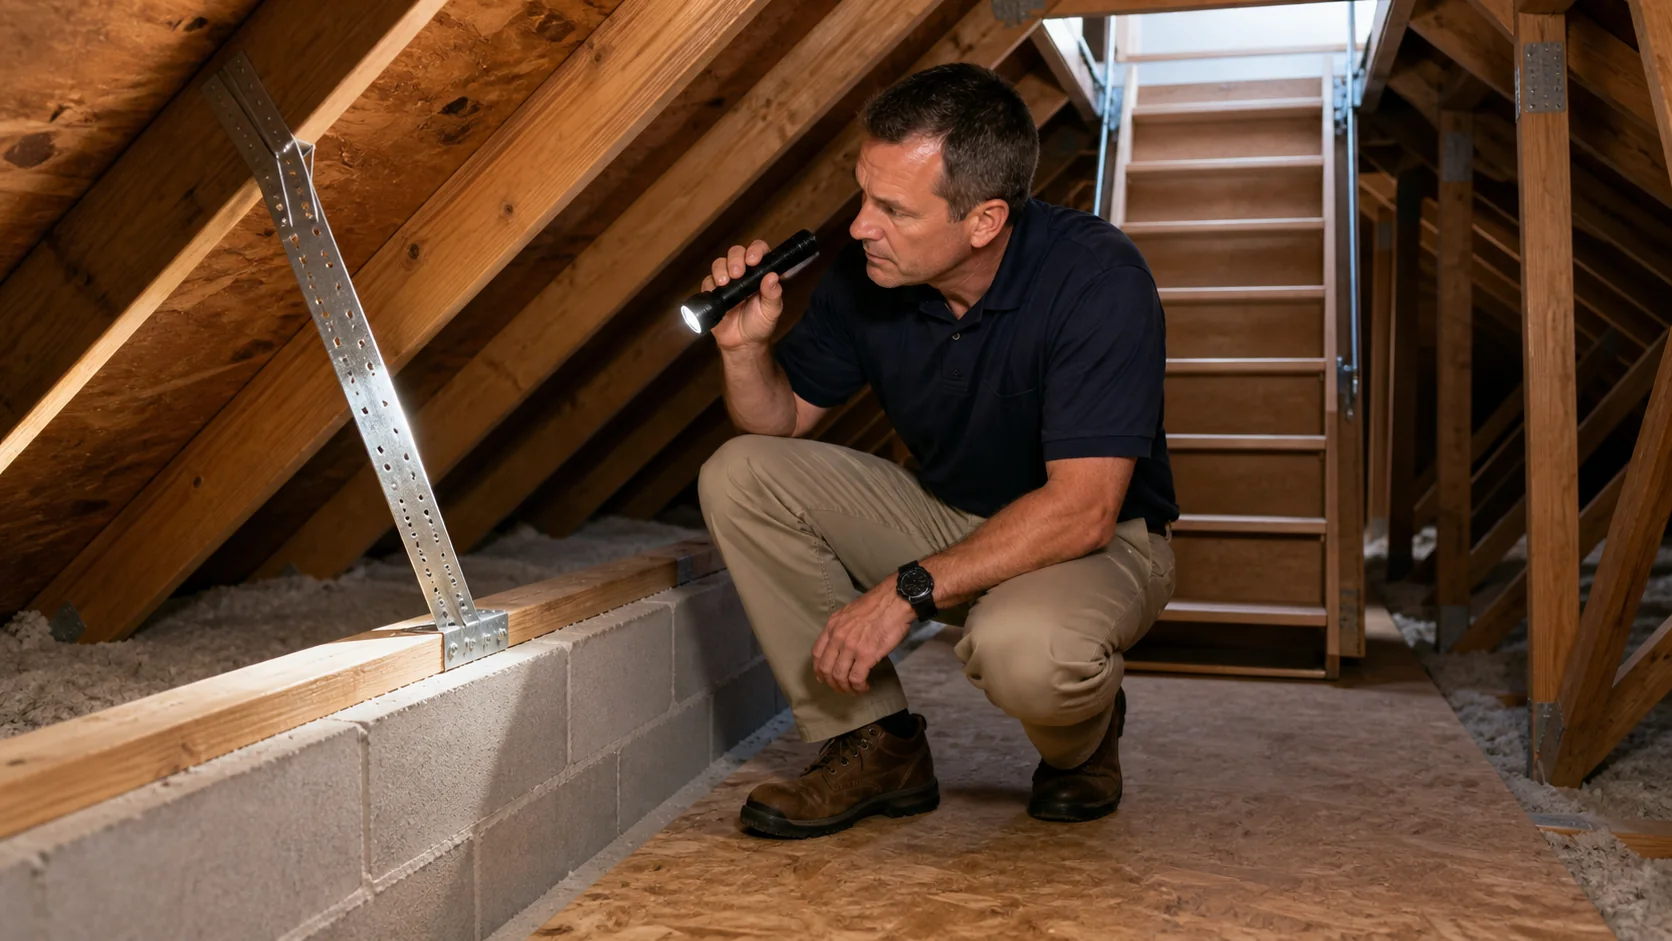
Because manufactured homes are more vulnerable to wind uplift than site-built homes, carriers commonly ask about the tie-down or anchoring system securing the home to its foundation.
Roof covering type and condition are also reviewed, similar to a site-built home, with older or damaged roofing more likely to raise concerns.
Which Florida Carriers Write Manufactured Homes, and Does Land-Owned vs. Park-Owned Change It?
Not every carrier that writes standard homeowners policies also writes manufactured home policies, and some that do treat land-owned homes differently from homes in a manufactured-home community.
Checking directly with an agent about current appetite is more reliable than assuming general availability, since this segment has fewer carriers overall.
What Does Manufactured Home Insurance Cost in Florida?
Manufactured home premiums are influenced by the home’s age, tie-down and wind-mitigation features, location, and coverage limits chosen, not a single statewide rate.
Because fewer carriers compete in this segment, shopping multiple carriers can matter even more than it does for standard homeowners coverage.
Frequently asked questions
Is a manufactured home insured the same way as a site-built home?
No. Fewer carriers write manufactured homes, and underwriting focuses heavily on tie-downs, age, and HUD compliance.
What if my home’s HUD label is missing?
This can complicate underwriting; a carrier or agent can advise on alternative ways to document the home’s age and standards compliance.
Does it matter if I own the land under my manufactured home?
Yes. Some carriers treat land-owned homes differently from homes in a rented-lot community.
 Ready to get coverage for this type of home?
Get a quote from your Florida-licensed agent
A licensed agent will follow up directly to help find the right coverage.
- Florida-licensed agent
- Help with all property types
- No obligation
- Quotes typically back within 24 to 48 hours