
How much does home insurance cost in Florida?
There is no useful one-price answer for every Florida home. Two homes on the same street can have different premiums because of the roof, rebuild cost, wind features, claims, coverage, and carrier.
Quick answers
Prices: real quotes I’ve seen, October 2024 to September 2026. Rules: Florida OIR filings and Fla. Stat. §626.9741. Last verified: September 2026.
What Florida Homeowners Actually Pay, and Where That Figure Comes From
Florida is one of the most expensive states in the country to insure a home, and prices vary widely even within one county. In the single-family (HO-3) quotes I’ve seen for Florida homes from October 2024 to September 2026, the median quote was about $4,200 a year and the higher end of what I see (the 75th percentile) was about $6,600. See the ranges for condos, rentals and mobile homes and by county.
Please read: these are ranges I see, not your price.
- These numbers come from real quotes I’ve seen, mostly for homes in the Tampa Bay area and a few other parts of Florida. They show what I typically see in those areas, not what every Florida homeowner pays.
- Your price depends on many factors: your exact location and distance to the coast, roof age and type, year built, construction, wind-mitigation features, coverage amounts, deductibles, claims history, and which carriers are writing in your area.
- I show the median (half of the quotes were at or below it) up to the higher end (about three in four were at or below it), rounded. Some homes quote below these ranges, and some quote well above them.
- Nothing on this page is a quote or an offer of coverage. The only way to know your price is a quote for your address.
Two homes a few miles apart, built in different decades with different roofs, can have premiums that differ by thousands of dollars. The only way to know your actual number is to get quotes for your specific address.
Why Florida Costs More Than the Rest of the Country
A handful of structural factors keep Florida premiums elevated regardless of any individual homeowner’s choices. The state’s peninsula geography and six-month Atlantic hurricane season create hurricane and storm-surge exposure that most of the country doesn’t face. Major storms, including Hurricane Ian in 2022 and Hurricane Michael in 2018, have each caused billions of dollars in insured losses. To stay solvent against that exposure, Florida carriers buy large amounts of reinsurance every year ahead of hurricane season. That reinsurance cost gets passed through to policyholders in the premium.
The market has also been through a period of real instability: multiple property insurers became insolvent in 2022 alone, and fewer competing carriers generally means less pricing pressure pushing rates down. Litigation and claims-abuse costs have historically been a major driver of Florida rates as well; the legislature passed reforms in December 2022 (SB 2-A) eliminating one-way attorney fee shifting and restricting assignment-of-benefits practices on property claims, and carriers and regulators have both pointed to those reforms as a factor in the market beginning to stabilize, though the effect on any individual renewal still depends heavily on the carrier and county.
What the Home Itself Changes: Roof, Age, Construction, Distance to Coast
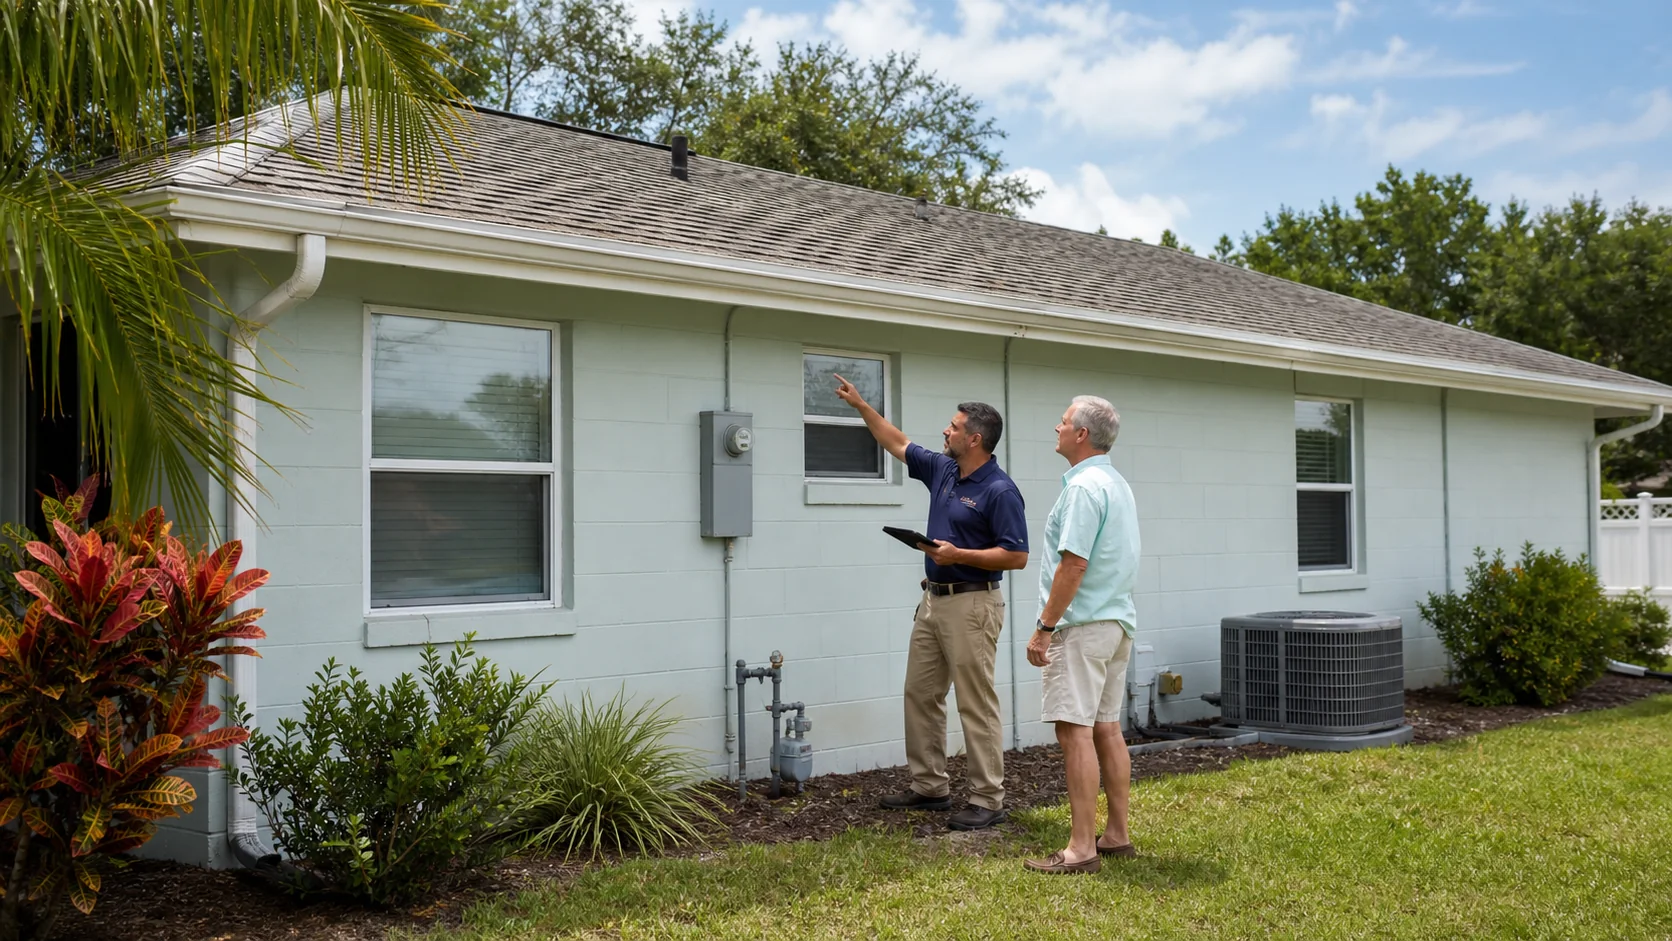
Your roof is one of the single biggest underwriting factors on a Florida policy. Many carriers restrict, surcharge, or require an inspection for roofs beyond 15 to 20 years old, regardless of visible condition. The roof covering itself matters too. Concrete tile and metal roofs are generally viewed more favorably for wind resistance than asphalt shingle. The features documented on a wind mitigation inspection (roof shape, roof-to-wall connections, opening protection, and more) directly affect both eligibility and pricing; see the wind mitigation inspection guide for what that report covers.
Construction type matters too. Masonry or concrete block (CBS) construction is typically rated more favorably than wood frame for wind risk. The year a home was built matters as well, because Florida’s building code was substantially strengthened after Hurricane Andrew, with further statewide updates over the following decades, so homes built to more recent code standards are generally viewed as lower risk. Distance from the coast is a major pricing input on its own, since wind speeds and storm-surge exposure both increase closer to open water. Homes near the coast frequently see higher premiums and, in some cases, more limited carrier options.
What Your Choices Change: Deductibles, Coverage Limits, Endorsements
Florida policies carry a separate hurricane deductible in addition to the all-other-perils deductible. The hurricane deductible is usually set as a percentage of your dwelling coverage limit, commonly 2%, 5%, or 10%, rather than a flat dollar amount. Choosing a higher hurricane deductible lowers your premium, but it also raises how much you pay out of pocket before hurricane coverage kicks in. That choice is a real trade-off. Your Coverage A (dwelling) limit should be set to your home’s replacement cost, not its market value; being underinsured on Coverage A can leave you exposed after a major loss, while significant over-insuring simply raises your premium without a matching benefit.
Optional endorsements move the number too: some carriers now offer actual cash value (rather than replacement cost) settlement specifically on older roofs in exchange for a lower premium, ordinance-or-law coverage adds cost but pays for code-driven rebuilding expenses, and sinkhole coverage is optional and priced separately from the catastrophic ground cover collapse coverage that’s a mandatory minimum on Florida policies. Reviewing each endorsement on a quote is the only way to know what you’re trading for a lower number.
What Your History Changes: Claims, Lapses, Credit-Based Scoring
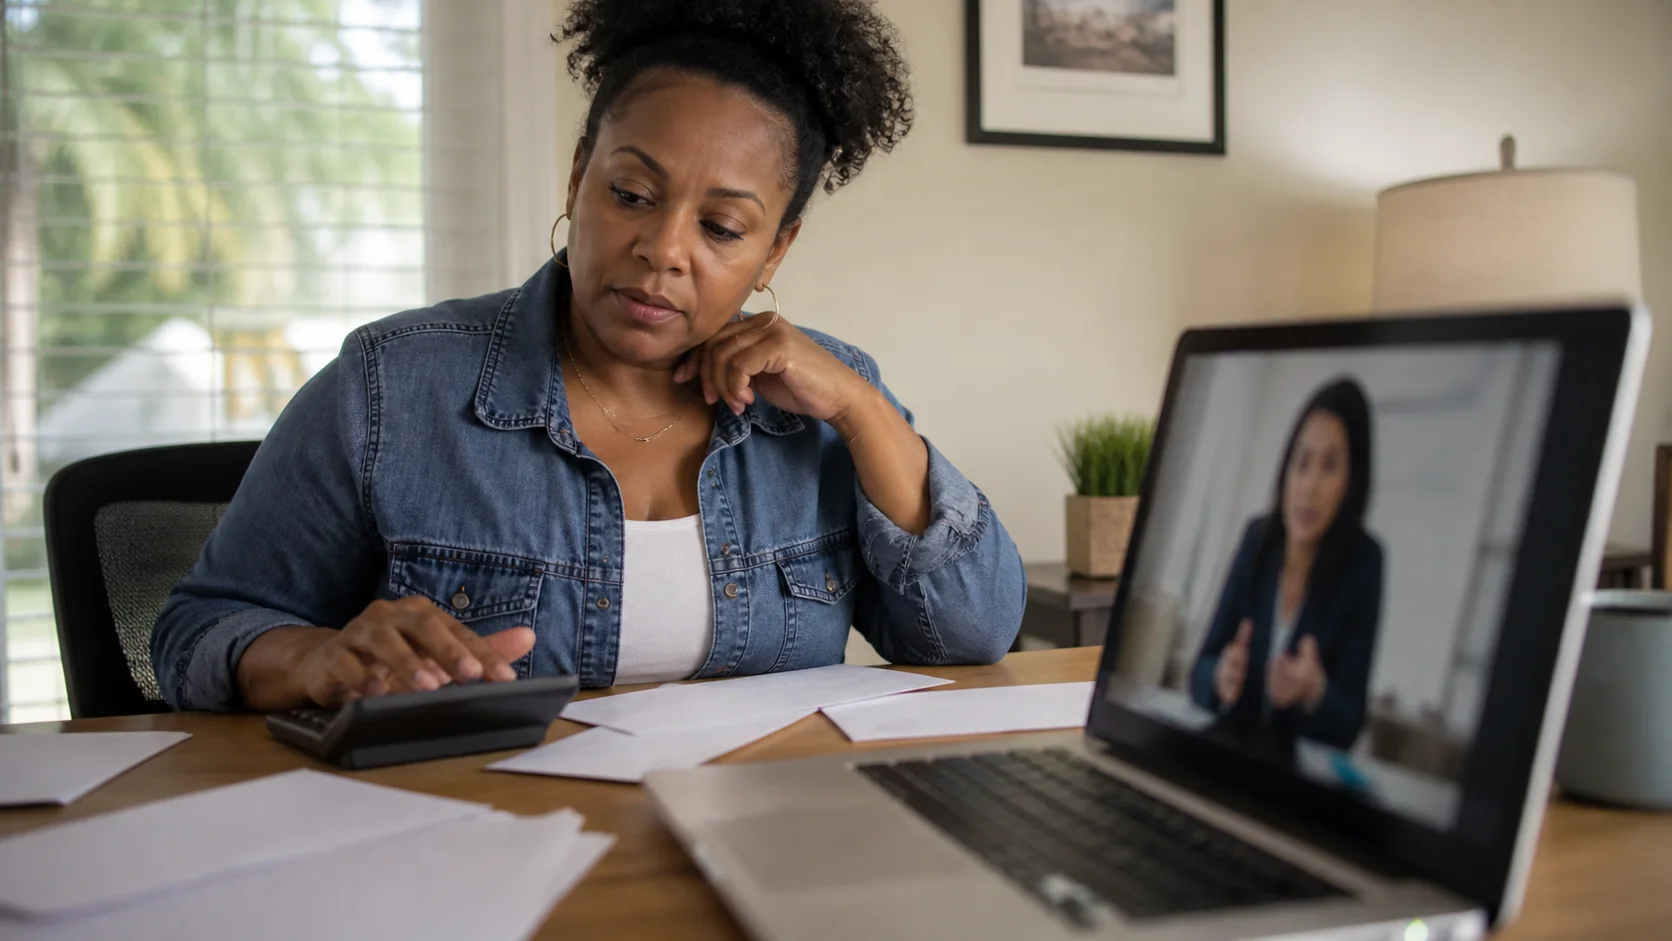
Insurers pull a claims history report (commonly a CLUE report) as part of underwriting. A prior claim on the property, even a modest one, can raise your premium at renewal. A gap or lapse in continuous insurance coverage is generally treated as a risk signal as well.
Florida law (Fla. Stat. §626.9741) permits insurers to use a credit-based insurance score as one factor in underwriting and rating homeowners policies, but it isn’t unrestricted: an insurer cannot base a decision solely on credit information, cannot use certain items such as medical collection accounts against you, and must disclose the top factors behind an adverse decision in specific, non-vague language. Insurers are also required to re-evaluate your credit information at least once every two years and adjust your premium favorably if your score has improved, and the law provides an appeal path if your score was affected by a divorce, the death of a spouse, or an involuntary loss of employment.
Which Discounts and Credits Are Actually Available in Florida
Florida law requires insurers to offer credits for wind mitigation features verified by a wind mitigation inspection. Hip roof shape, reinforced roof-to-wall connections, secondary water resistance barriers, and impact-rated openings or shutters can each reduce your premium, though the dollar value of each credit is set by the individual carrier’s filed rate plan and varies from company to company. A newer roof typically qualifies for its own discount independent of the wind mitigation credits. Beyond home-specific features, common discounts include bundling your homeowners and auto policies with the same carrier, monitored burglar and fire alarms, gated-community or hurricane-shutter credits, and a claims-free history discount for policyholders who haven’t filed in several years.
Homeowners who complete mitigation upgrades through the My Safe Florida Home program often become eligible for these same wind mitigation credits once the completed work is reflected in a new inspection.
Why Two Quotes on the Same Home Can Differ So Much
Every insurer licensed in Florida files its own rate manual with the Office of Insurance Regulation, and different carriers weight roof age, construction type, coastal distance, claims history, and credit-based scoring differently from one another. Some carriers deliberately specialize in, or avoid, certain risk profiles. A company that limits how much older-roof business it writes will price an older home punitively, or decline it outright, while a carrier that specializes in exactly that profile may quote it competitively. Each carrier’s own reinsurance program and how concentrated its existing book of business already is in your county also feeds into its price for your specific risk.
Citizens Property Insurance Corporation exists as the state’s insurer of last resort for homes the private market won’t write at a reasonable price, so a Citizens quote is a backstop, not a benchmark for what the broader market would charge. Because of how much variation exists carrier to carrier, shopping multiple independent quotes for the same home is one of the few actions within a homeowner’s control that reliably affects the final number.
 Need a specific insurance company?
Get a quote from your Florida-licensed agent
Share a few details about your home, and our team will follow up to review your request and explain the next step.
- Florida-licensed agent
- Help with all property types
- No obligation
- Quotes typically back within 24 to 48 hours
Frequently asked questions
Why can two similar homes on the same street pay very different premiums?
Because premiums turn on home-specific factors: the roof’s age and material, rebuild cost, documented wind-mitigation features, claims history, coverage and deductible choices, and which carrier is quoting. The only way to know your actual number is to get quotes for your specific address.
Did Florida’s 2022 insurance reforms lower prices?
The December 2022 reforms (SB 2-A) eliminated one-way attorney-fee shifting and restricted assignment-of-benefits practices on property claims. Carriers and regulators point to those reforms as a factor in the market beginning to stabilize, though the effect on any individual renewal still depends heavily on the carrier and county.
Which construction types are rated most favorably?
Masonry or concrete block (CBS) construction is typically rated more favorably than wood frame, and concrete tile and metal roofs are generally viewed more favorably than asphalt shingle for wind resistance.
Where to go next
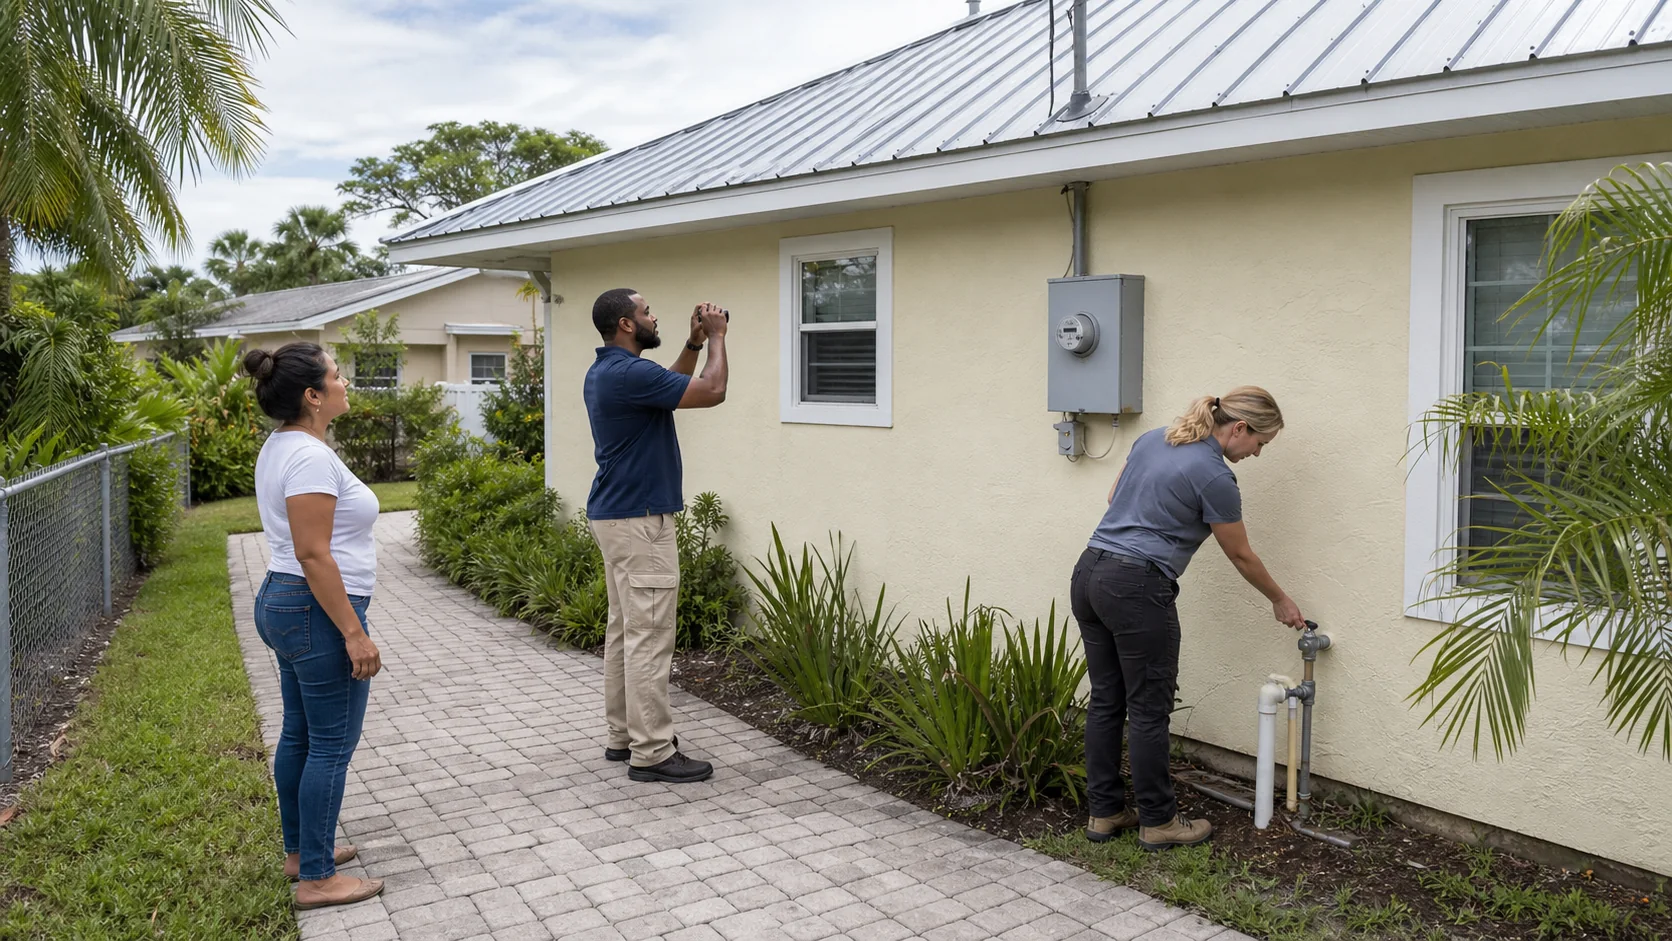
Guides & help center
Everything educational, in one place.
Understanding your quote
Every coverage on a Florida policy, explained.
Eligibility tables
Which carriers will write a home like yours.
Carrier directory
Full profile for each carrier in our directory.
Insurance pricing by property type
What Florida homeowners actually pay, and what moves the number.