
Insurance for a coastal Florida home
A coastal home may face wind, storm surge, flood, salt, and limited carrier choices. The exact address and distance from water can matter.
Quick answers
Sourced from Florida Statutes § 627.701 and Florida DFS homeowners guidance. Last verified: August 2026.
What Is the Wind Pool, and How Do I Tell Whether My Address Sits Inside It?
Florida’s wind pool refers to areas, generally along the coast, where windstorm risk is high enough that it affects which carriers are willing to write coverage and how that coverage is structured.
An agent or carrier can confirm whether a specific address sits inside a designated wind-pool or high-velocity hurricane zone, since the boundaries are set at the state and county level rather than by a simple distance-to-water rule.
Wind, Flood or Hurricane: Which Policy Is Actually Being Quoted to Me?
A standard homeowners policy generally includes windstorm coverage as part of the policy (sometimes as a separate wind endorsement in coastal areas), but it does not include flood coverage, which is a separate policy entirely.
“Hurricane insurance” isn’t usually a distinct policy. It typically refers to the wind coverage within the homeowners policy, subject to its own hurricane deductible.
What Is a Hurricane Deductible, and When Does It Apply Instead of the AOP Deductible?
A hurricane deductible, often calculated as a percentage of the dwelling coverage amount, applies specifically to damage from a hurricane, while the all-other-perils (AOP) deductible applies to most other claims.
Understanding which deductible applies, and how large the hurricane deductible is in dollar terms, matters when comparing coastal quotes.
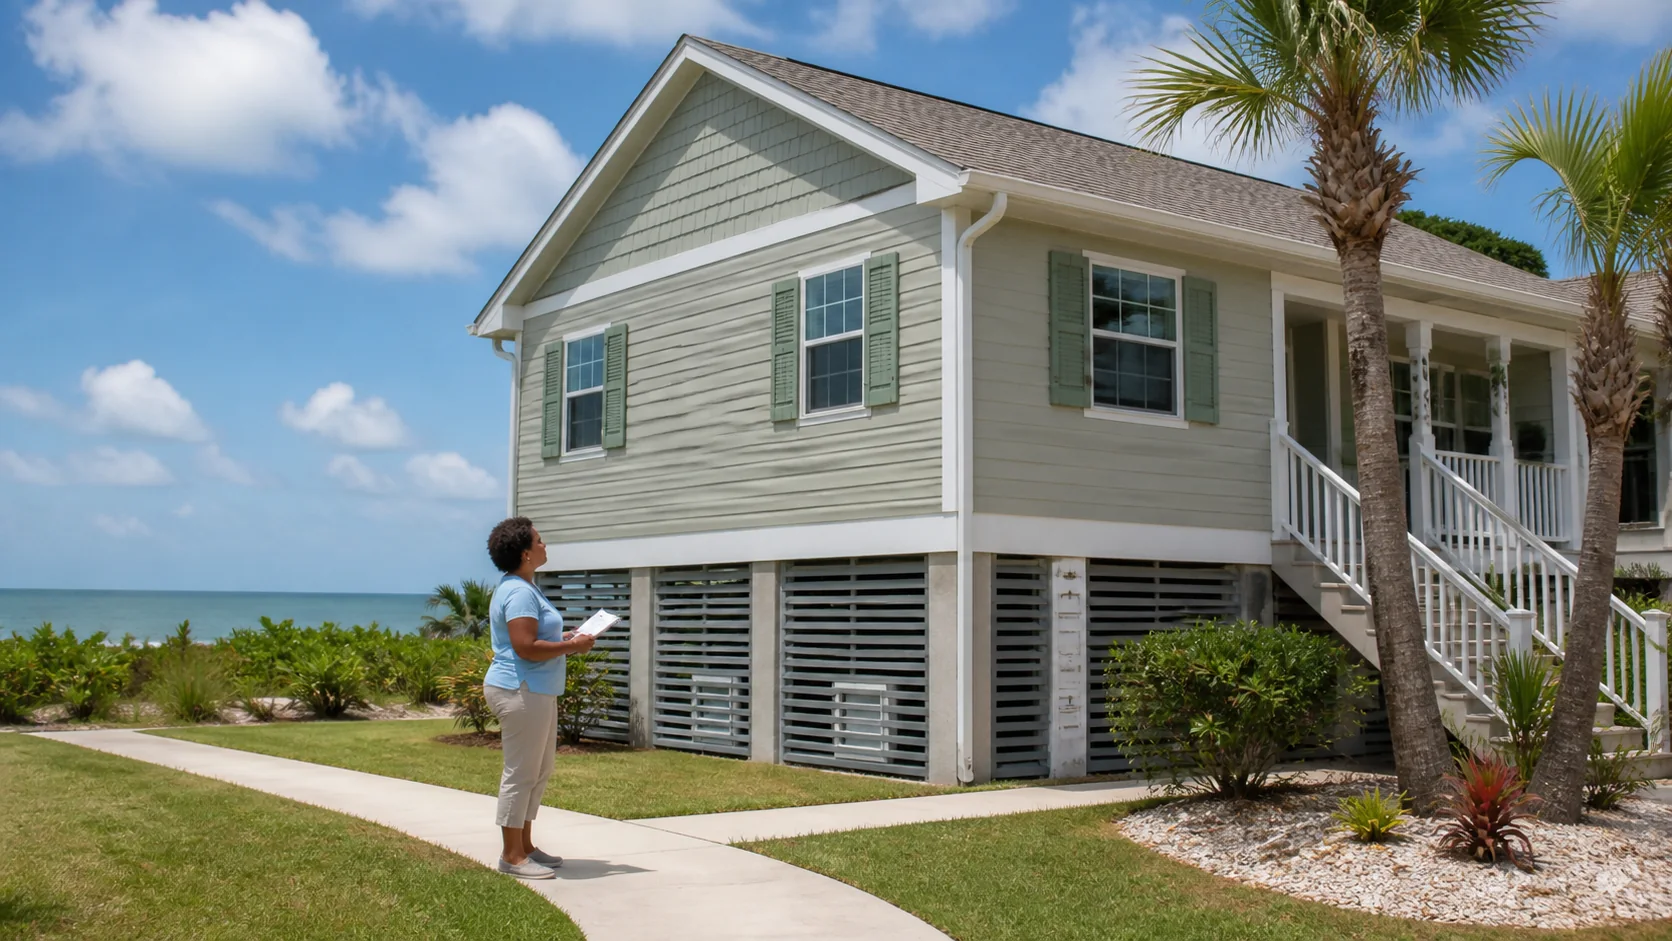
Which Openings, Roof Shape and Elevation Details Do Coastal Carriers Ask About?
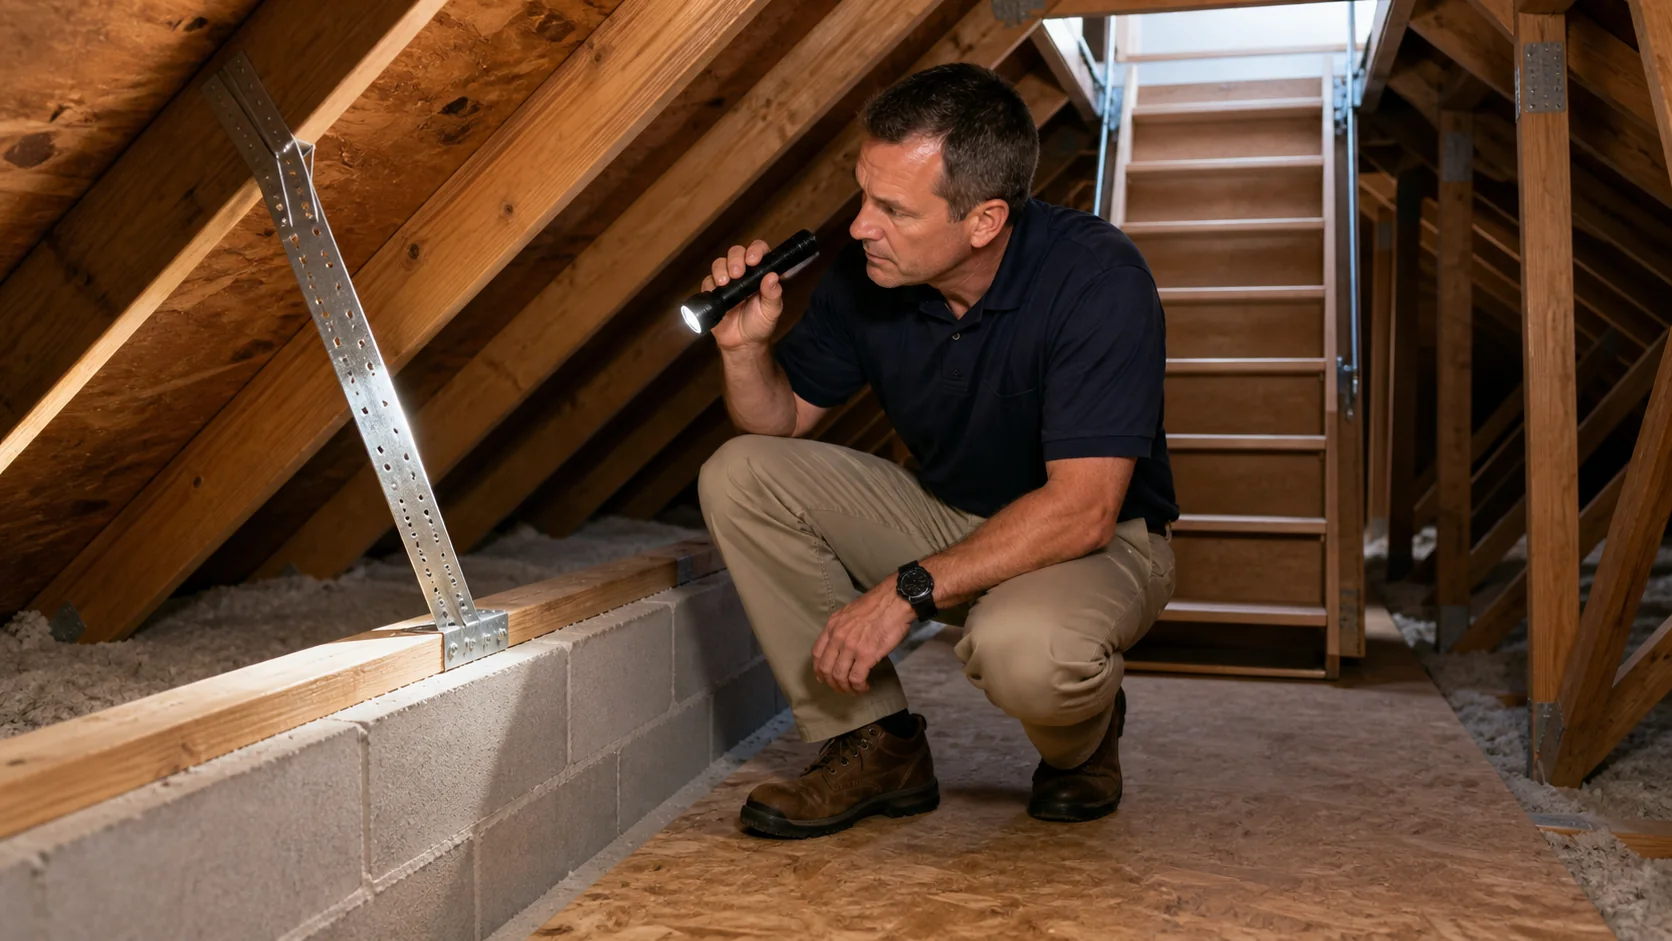
Coastal underwriting commonly looks at roof shape (hip roofs are generally viewed more favorably than gable roofs in high-wind areas), opening protection such as impact windows or shutters, and the elevation of the home relative to base flood elevation.
A wind-mitigation inspection documents many of these features and can affect both eligibility and pricing.
Which Carriers Write Coastal Florida Homes, and Which Stop at a Distance From the Water?
Some carriers set a hard distance-to-coast limit beyond which they will not write new business, while others evaluate coastal homes individually based on construction and mitigation features.
Because these rules vary carrier to carrier and change over time, checking current appetite directly with an agent or the carrier is more reliable than relying on general assumptions.
Frequently asked questions
Is flood insurance included in a coastal homeowners policy?
No. Flood coverage is a separate policy, typically through the National Flood Insurance Program or a private flood carrier.
Does a wind-mitigation inspection lower my premium?
It can qualify a home for wind-mitigation credits, though the specific savings depend on the carrier and the features documented.
What is considered “coastal” for underwriting purposes?
Definitions vary by carrier: some use a strict distance-to-water measurement, others use designated wind-pool zones.
 Need a specific insurance company?
Get a quote from your Florida-licensed agent
Share a few details about your home, and our team will follow up to review your request and explain the next step.
- Florida-licensed agent
- Help with all property types
- No obligation
- Quotes typically back within 24 to 48 hours